The internet is obsessed with making you rich. Here’s what it leaves out
Most get-rich-quick investing content shows you the upside and hides the rest: the losses, the luck and the fact that the seller often earns more from selling the dream than from investing. Apparently everyone retired at 28 and can teach you how for $49.99. Ten years in, I can tell you the real version is slower, duller and works far more often.
Not financial advice. This is general education drawn from my own ten years of investing, not personal investment, tax or legal advice. Every number here is a hypothetical example unless a source says otherwise.
What does a profit screenshot actually prove?
Almost nothing. A screenshot of a $10,000 profit is exciting, but ask:
- Was there a $30,000 loss last week?
- Was the position ever actually closed?
- Is the account even real, or a demo?
You rarely get the full story. Nobody posts the screenshot of the month they gave it all back.
Why does everyone look like a genius in a bull market?
When almost everything in a market is rising, luck looks like skill. I’ve had years where nearly anything I touched went up, and I’ll be honest, it felt like talent. It wasn’t. The useful question about any strategy is what happens to it when markets fall and nobody is excited anymore.
How do you tell education from marketing?
Some financial educators are excellent. The quick test: does this person explain the downside as clearly as the upside? Risk isn’t a footnote to mention after the pitch. It’s half the story. Other warning signs:
- Guaranteed or “risk-free” returns.
- Pressure to act now, or a countdown timer.
- Private group chats where someone “has a tip”.
- No mention of fees, taxes or losses.
The SEC regularly warns about this. Its alerts on social media and investment fraud and AI-related investment scams say never to make investment decisions based only on what you see on social media, and that a celebrity endorsement doesn’t make an investment legitimate.
What does real wealth-building look like?
There’s a glamorous version and a boring version.
- Glamorous: cars, screenshots, predictions, urgency.
- Boring: saving regularly, growing what you earn, controlling spending, spreading your investments, and giving good decisions time.
Boring doesn’t photograph as well. It’s also what actually worked for me. For the boring version step by step, see if I had to learn investing all over again.
Pylcrow’s take
The internet rewards attention, not accuracy. Someone selling financial dreams may make more from the dreams than from investing. Start now, but start with the boring version. Apply the Pylcrow 3-question test to every pitch: what do I own, how does it make money, how can I lose?
Frequently asked questions
Are finfluencers reliable?
Some are thoughtful, many are not, and few are regulated like licensed advisers. Treat their content as a starting point to check, never as advice.
Are paid trading courses worth it?
Be careful. If the seller’s main income is the course, their incentive is selling courses, not your returns. Free official resources cover the basics well.
How can I spot an investment scam online?
Guaranteed returns, pressure to act fast, unsolicited tips, and requests to move to private chats or unusual payment methods are classic red flags.
Is it possible to get rich quickly by investing?
A few people do, mostly through luck or extreme risk, and you mostly hear from the winners. For most people, wealth builds slowly.
What should you read next?
This is part 4 of 10 in Pylcrow Money: the real picture, a starter series written from ten years of getting some of this right and some of it wrong.
Next in the series: Dividends explained: what’s the catch?
The full Pylcrow Money starter series:
- Investing explained: it’s not as complicated as people make it sound
- Before you buy your first stock, read this
- ETFs explained: how one purchase can mean owning hundreds
- The internet is obsessed with making you rich
- Dividends explained: what’s the catch?
- Stocks, bonds, gold and cash: what does each one do?
- Why your first $1,000 matters more than you think
- Passive income isn’t as passive as they tell you
- The market crashed. Do you need to do anything?
- If I had to learn investing again, this is where I’d start
Before you act on any of this
Not financial advice. Pylcrow Money is general educational material, not individual investment, legal or tax advice. All examples are hypothetical and are not a forecast or a promise of returns. Investing involves risk, including losing money. Which funds you can buy, and the fees, taxes, rules and currency costs that apply, depend on where you live and on your own situation. If you are unsure, speak to a licensed adviser in your country. Read our full disclaimer.
By Pylcrow. Last reviewed: November 2, 2026.
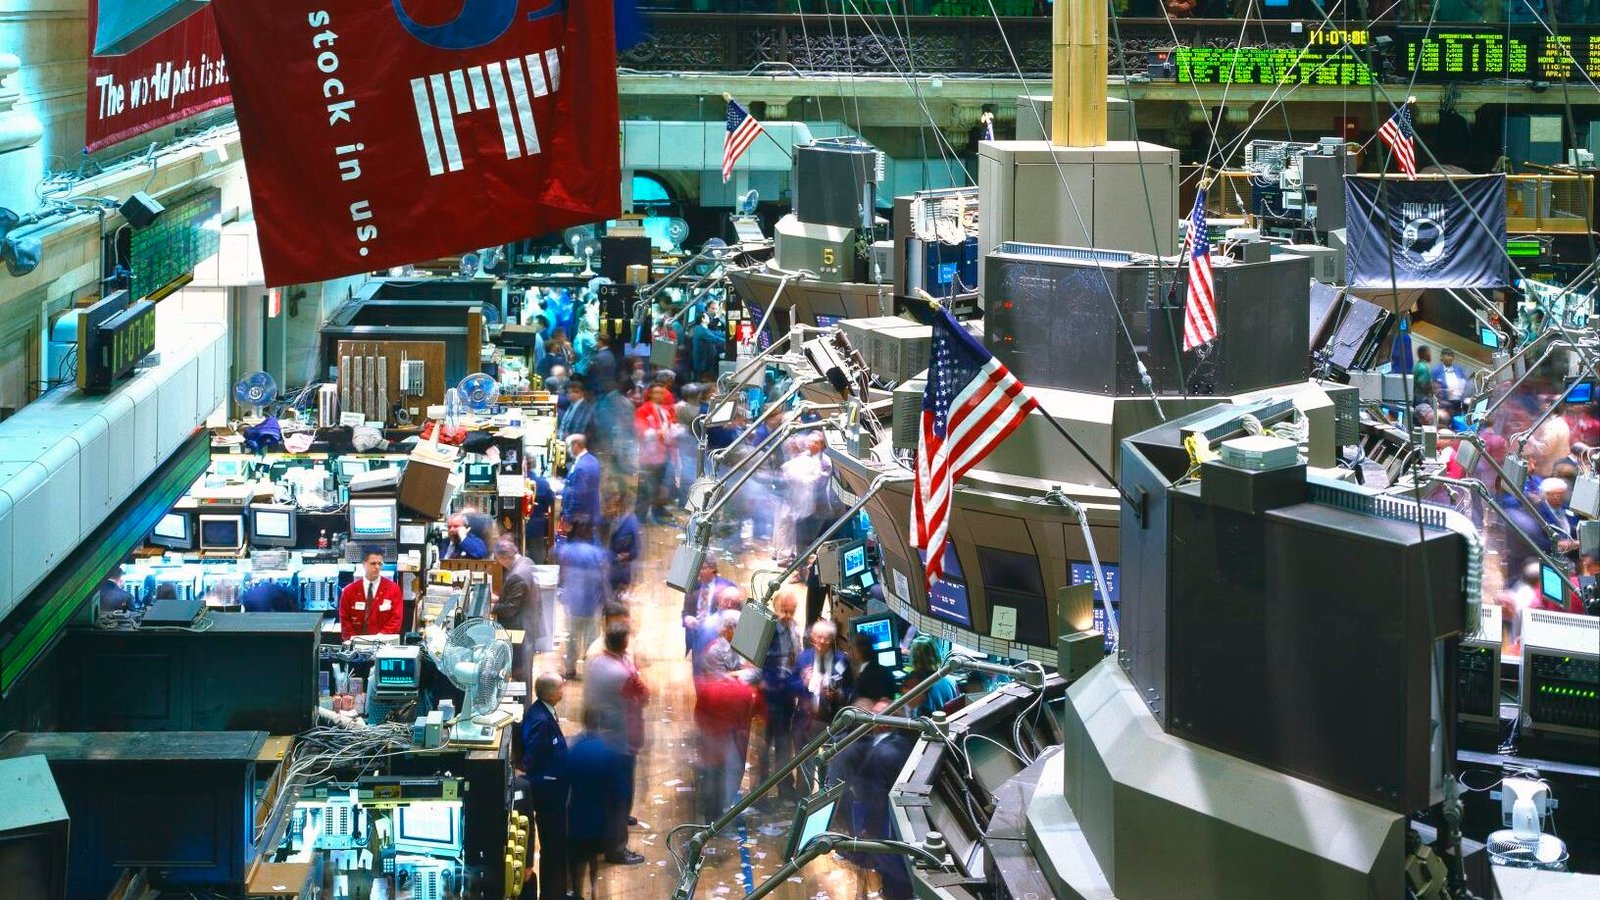
Sources: Investor.gov (SEC): social media and investment fraud; Investor.gov (SEC): social media and stock tip scams; Investor.gov (SEC): artificial intelligence and investment fraud. Top image: the New York Stock Exchange trading floor by Carol M. Highsmith, Library of Congress, public domain via Wikimedia Commons.